Summary – A top-down review of interesting calls and comments made last week in Treasuries, monetary policy, economics, stocks, bonds & commodities. TAC is our acronym for Tweets, Articles, & Clips – our basic inputs for this article.
- Editor’s Note: In this series of articles, we include important or interesting Tweets, Articles, Video Clips with our comments. This is an article that expresses our personal opinions about comments made on Television, Tweeter, and in Print. It is NOT intended to provide any investment advice of any type whatsoever. No one should base any investing decisions or conclusions based on anything written in or inferred from this article. Macro Viewpoints & its affiliates expressly disclaim all liability in respect to actions taken based on any or all of the information in this article. Investing is a serious matter and all investment decisions should only be taken after a detailed discussion with your investment advisor and should be subject to your objectives, suitability requirements and risk tolerance.
1.Thanks & Very Best Wishes
Rarely have we seen such a gracious act from anyone, let alone a Government official! Treasury Secretary Bessent stunned Rick Santelli & the entire investment world by his letter thanking Rick Santelli for his service to the Country, Financial Markets and the American people and saying truthfully and clearly:
- “Television has produced plenty of market commentators over the years, but there has only ever been one Rick Santelli “
We have always believed and we continue to insist that the fundamental backbone of the US Financial System is the US Treasury Market. There is nothing like it in the world in its depth, size, power & the best accuracy in pricing. And Rick Santelli has done more than anybody to publicly serve this great engine of this magnificent country.
We got introduced to US Treasuries by listening to Rick Santelli on CNBC. He was honest & fought for his views & understanding of what the Treasury market was saying. The best teacher we have seen.
Thanks very much Maestro Rick!
2. Markets Last Week
2.1 US Indices:
- VIX down 6.7% to 14.81; Dow down 1.7%; SPX down 8 bps; RSP down 1.2%; NDX up 94 bps; RUT down 1.5%; MDY down 1.8%; XLU down 3%; SMH up 79 bps; SOXL up 1.5%; NVDA down 1.8%.
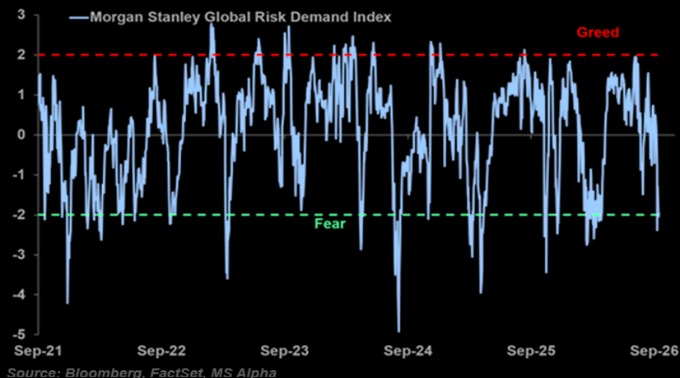
- The Market Ear@themarketear – 9-20 – counterintuitively, Morgan Stanley’s Global Risk Demand Index has moved into its “fear” zone.
and,
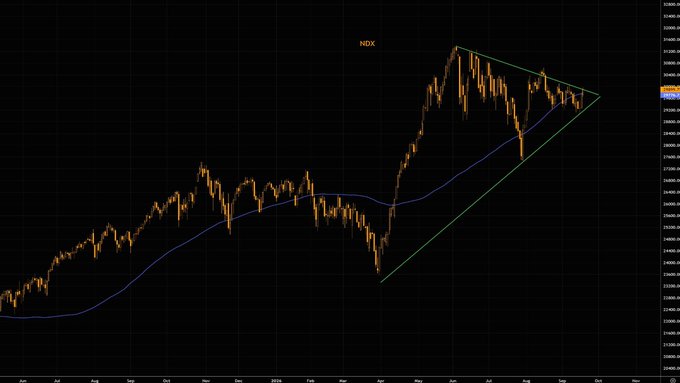
A bullish divergence!
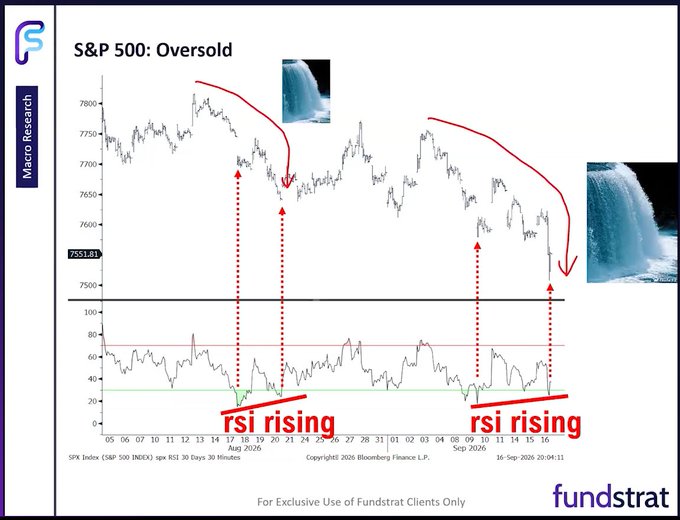
- Mike Zaccardi, CFA, CMT 🍖 @MikeZaccardi – 9-18 – Look at @fundstrat calling out some bullish $SPY divergence recently... I like it! @fundstratdirect @MarkNewtonCMT – https://fundstratdirect.com/macro-strategy/macro-minute/2026/09/16/video-macro-minute-fed-raising-25bp-and-statement-is-max-hawkishness-and-co/
Getting to our favorite sector:
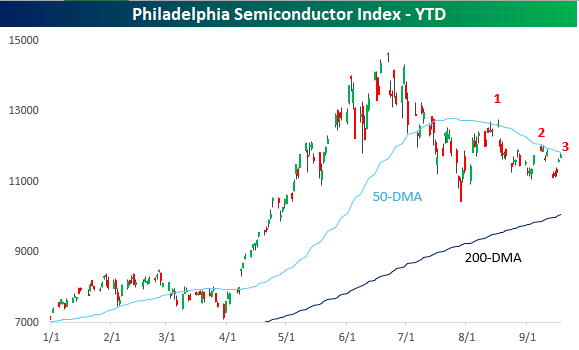
- Bespoke@bespokeinvest – 3rd time the charm for semis and the 50-DMA, or not a chance?
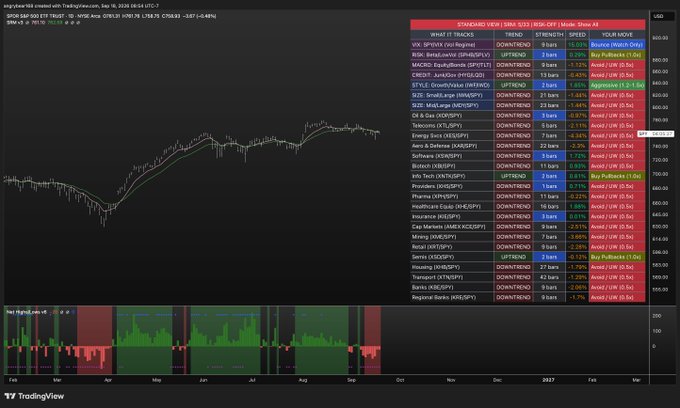
But are Semis the lone warrior now?
- Trader Z@angrybear168 – $SPY – overall environment is still challenging but seeing improvements, $SMH acting as the lone warrior out here.
And the opposite of Semis?
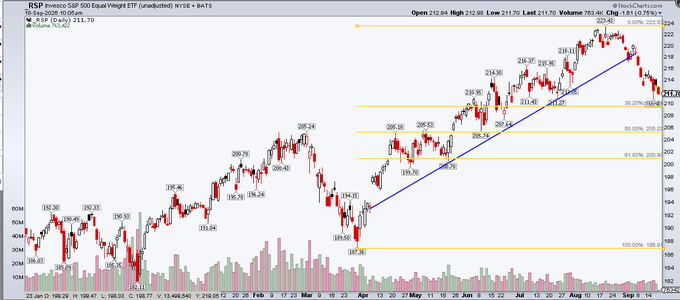
- Mike Zaccardi, CFA, CMT 🍖 – @MikeZaccardi – $RSP continues to look sickly
$209-$210 is the 38.2% Fibo of the March-to-August rally
When does Small act large? Way Large!
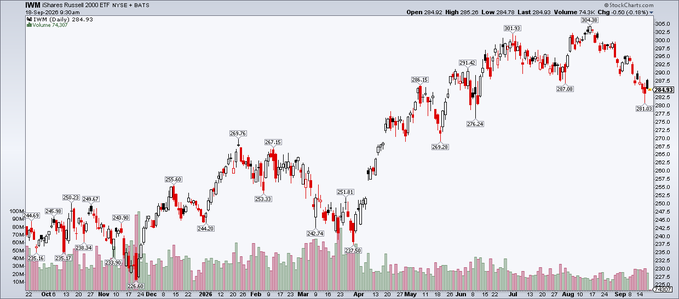
- Mike Zaccardi, CFA, CMT 🍖@MikeZaccardi – 9-18 – $IWM – almost a 7% drawdown off the high from 5 weeks ago
This has been a year for the Warren Pies style of going to benchmark weight for equities at an intermediate high & then going back to overweight after a downturn. True to that, Pies went back to Overweight Equities on Friday September 18. His reasons were simple – He thinks this rate hike represents a two-hike mini-cycle and he says the Fed rate hike this week has “cleared the decks” and enabled him to “upgrade equities“. But he hasn’t upgraded bonds yet saying “the 2-year yield is at fair value & the 10-yr yield may have another 10-15 bps to rise“.
Before Warren Pies on Friday, came John Flood, Execution Head for Equities at Goldman Sachs. He showed how direct access to large client execution helps one to understand, maintain & pivot as needed to major market movements:
- “There is extreme hedging happening in the markets to combat all the macro headlines that we have to deal in client conversations – Oil, Rates. Geopolitics. But when we look at earnings, they have been stellar, Q2 earnings season was one of the best we have seen … it wasn’t just AI; S&P 500 Q2 earnings, ex-AI, ex-Energy, still grew 14% year/year; we think this trend is intact & we are bullish because earnings are very very solid”
Then he turned to Fed & interest rates:
- “Market is right now pricing in 3 more rate hikes before year-end of 2027. Our economists think we get 1 more 25 bps rate hike this year and 2 rate cuts next year. So it would take a lot for the market to have a hawkish surprise; that being said when institutional investors rotate out of equities into bonds, its all about the speed of move in interest rates. So if we see the 10-year yield hit 5.5% before Halloween (a 2 standard deviation move over a 1-month period), that is when you start to see assets move away from equities into bonds, that would be concerning to me”
Of course, you can’t let an Execution Head of Sales leave without speaking about Seasonality of mutual funds tax loss in September picture!
- “Seasonality to me, where we see it most – September is the #1 fiscal year-end month for the mutual fund community; … you see a lot of tax-loss selling … I would not be surprised to see a continued chop thru September because of these tax loss sales… expect the volatility to continue … but when you have positive GDP growth, positive earnings growth, light positioning, negative sentiment, that’s usually a solid brew to buy stocks”
2.2 MAG 7:
- AAPL up 1.2%; AMZN down 1.2%; GOOGL up 3.3%; META up 2.7%; MSFT down 37 bps; NFLX down 7.3%; SMH up 79 bps; SOXL up 1.5%; NVDA down 1.8%; MU up 4.2%; SNDK up 9.7%; IBM down 5.7%; IGV up 2.8%; CRM down 4%; PANW up 10%; NOW up 2.2%; PLTR up 6.2%;
To get back to Warren Pies from the above:
- “this is going to be a tech-led rally; hyperscalars first & then Semis right after that; Nebius hiked their on-demand GPU rates – everything we see is crazy demand for compute; So be long compute, hyperscalars, semis“
Going back above to the comments of John Flood, Execution Head for equities at Goldman Sachs, he was bullish on Software saying Software is where Semis were 8 months ago and added:
- “positioning there (in software) is very light; hedge funds have started to cover shorts; there is no length in this sleeve in the market; specifically within Software, we like Cyber-Security & data infrastructure; protect the home front … organize data in 2 themes that institutional investors are going to start leaning into“
2.3 Key Financials:
- BAC down 7.9%; C down 5.1%; GS down 8.5%; JPM down 1.8%; KRE down 1.6%; EUFN down 2.8%; SCHW down 1.9%; APO down 2.4%; BX down 2.8%; KKR down 2.3%; XHB down 2.1%; ITB down 2.4%; NAIL down 5%;
After all the positive stuff earlier, we feel a degree of comfort in speaking about what concerns us. And that, in short, is the performance of the Banks in what should be a positive week for risk.
To begin with, how the heck can BAC & GS be down 8% on the week with C down 5.1% in a week in which long rates fell a bit? Being utter novices in credit, we first jumped to the scary spectacle held above called “private credit”. But notice that the big “private credit banks” are down less than half of the big money-center banks.
Then we saw a supposedly stock-bullish clip of John Kolovos, Macro Risk Advisors head of technical strategy on Thursday, September 19, the day after the Fed. He is tactically bullish S&P 500 but analytically concerned and if S&P maintains 7670 & crosses above 7700, then he will get analytically bullish as well.
That being out of the way, we were really struck by what he said in response to a Melissa Lee question at minute 1:24. At that moment, the bottom-line under the screen showed “Credit Spreads near Bear Territory“. Kolovos explained that his model captures CDS Spreads, Mortgage Spreads & all types of bond indicators to measure what is going on in the Macro Environment. And he announced that:
- “Bond Market Financial Condition Model is about ready to go into Sell Territory by going above the 50 line. Last time it did so was in 2025 when it was a mini-bear market & before that in 2022 when it was a proper bear market. (It is) very very close to that level right now… “
Leaving aside our personal view that a bear market in credit should be described as “improper” instead of proper, Kolovos went to highlight China stocks, Euro stock 600 index & “many other cross assets” that are showing similar “improper” bear market warnings.
We candidly don’t understand how credit comfort is measured. How in particular is the impact of sharply rising gas prices on the financial comfort of the average American family reflected in credit indicators is a mystery to us? All we can do is watch clips like the one below & wonder how realistic it is:
And then the tragic reality expressed by those who are forced to use Diesel. Sorry the clips we found have unsavory language & so we can’t use them. Also we can’t follow the high-technical content shared by experts like Paul Sankey in his clip Why Diesel Prices Are Exploding and Who’s Getting Rich. So we simply watched the first several minutes of the clip “$10 Diesel by December” – JPMorgan Has No Clear Oil Endgame.
So is it any wonder that the Credit Spreads model of Mr. Kolovos is about to break above the 50-level? But allow us to say what we wonder now above all. When diesel/oil prices shoot up & “inflation” explodes, how does the Fed react? Do they shout “inflation” or do they shout “recession ahead”?
May be that is why the private-credit banks fared better than the money-center banks this past week! Because public or non-private credit is hugeee in scale compared to private credit!
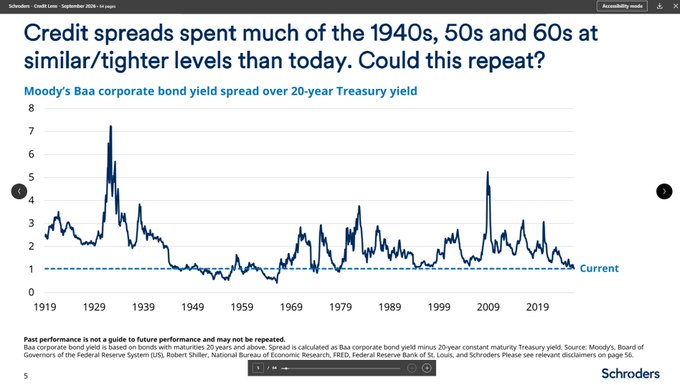
On the other hand, is it possible that the problem lies with the Credit Model of Mr. Kolovos? Is it one of those models that keep telling us that U.S. Dollar will not make it eventually? Why do we wonder so?
2.4 – Dollar & Metals
- UUP up 1.1%; DXY up 1.1%; Gold up 75 bps; GDX down 1.7%; Silver up 3.2%; Copper up 2.6%; CLF up 3.7%; FCX up 66 bps; MOS down 2.8%; Oil down 94 bps; Brent down 1.6%; OIH down 5.2%; XLE down 1.3%; PBR down 1.9%;
Frankly, we like the message of this section – Dollar Up, Gold Up, Copper (& Semis) Up, Oil Down. Our own feeling is that if Oil prices went down & stayed down, the markets would look & feel much better.
2.5 – International Stocks:
- EEM down 1.2%; EMXC down 1.3%; FXI down 49 bps; KWEB up 93 bps; BABA up 3.6%; EWZ down 1.8%; EWY down 3.9%; EWJ down 1.6%; EWG down 1.7%; INDA down 1.1%; INDY down 1.1%; EPI down 1.5%; SMIN down 1.6%; IBN down 4.2%; HDB down 77 bps;
How is Western Europe coping with both the rising price of oil & the increased difficulty in importing it? Apparently, Diesel is not solely America’s problem. Below is France:
Our basic question in all this is simply whether the October-December 2026 period begins to resemble the October-December 1990 period when the Middle East was embroiled in conflict, Treasury rates surged to 9%, Oil shot up and the U.S. stock market fell hard.
We hope & we pray that the above is just wildly exaggerated and the U.S. Economy has AI to deliver the necessary growth.
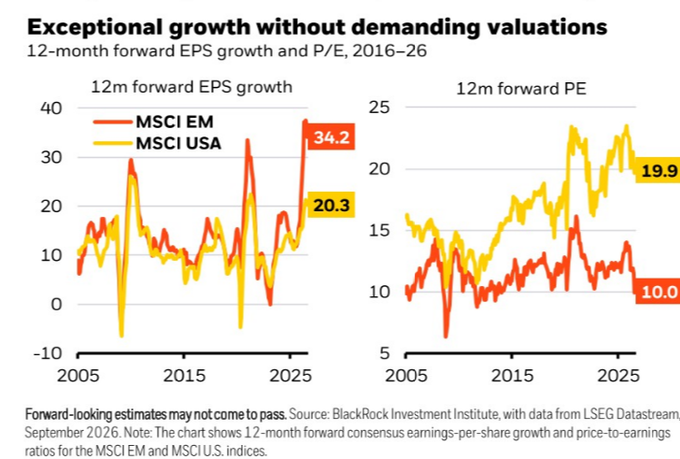
Or even better, is the above nothing but nonsense and all is right with the EM world as BlackRock suggests?
2.6 Treasuries & Interest Rates
- 30-year Treasury yield down 2.5 bps on the week; 20-yr yield down 1.1 bps; 10-yr up 3.1 bps; 7-yr yield up 6.1 bps; 5-yr yield up 7.8 bps; 3-yr yield up 12.2 bps; 2-yr yield up 13 bps; 1-yr up 7.3 bps;
- TLT up 47 bps; EDV up 1%; ZROZ up 1.1%; HYG down 9 bps; JNK down 6 bps; EMB up 4 bps:
Any decisive move post Fed decision?
- Jeffrey Gundlach@TruthGundlach – The 30 year UST yield is right back to where it was before the micro hike on Wednesday.
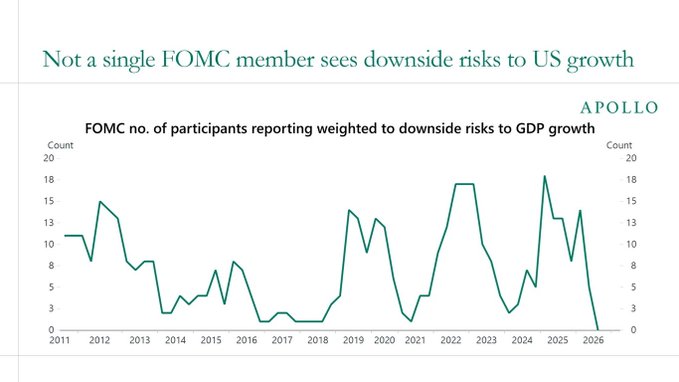
Jim Paulsen said Chair Warsh was emulating Alan Greenspan. BofA’s Hartnett said that “No Fed has been this terse since Volcker“. Any one to break the Volcker-Greenspan tie?
- Mike Zaccardi, CFA, CMT 🍖 @MikeZaccardi – 9-18 – Torsten at Apollo: Warsh Starting to Look Like Volcker; Fed Chair Kevin Warsh has been remarkably consistent. He has repeatedly said the Fed will deliver price stability. Wednesday’s rate hike shows that he means it.
Talking is talking but did any big-shot actually do anything? You can guess who would actually do something! The eminent Bob Michele of JPMorgan said on Bloomberg:
- Well, from our perspective, the market has gone an awful long way. The front end is pricing in approximately four rate hikes. And then the long end is pricing in a level of steepness to the front end that you would expect if you get 7500 basis point of rate hikes. So it looked awfully bearish. Uh, to us, I think we’ve reached the point of maximum pain. Uh, and to be honest, this morning in London we were in buying.
What were they buying?
- “30 year bonds, ten year bonds, 20 year bonds that were left for dead earlier this week, the long end of the US, Japan and Australia backing up the tariffs gone too far above not just the US then Japan and others too. It’s totally the top of large on the dominoes are starting to fall. The central banks and it started with the ECB. It now goes to the fed. And on Friday we expect the Bank of Japan. That’s the first thing you need are for the central banks to establish their credibility. I think Treasury Secretary Bessent is doing his best to stabilize the long end. He’s got the firepower to do more if he wants to the long and just got two cheap and two on anchor, it’s starting to stabilize.“
Then he added:
- “This is the first ingredient. The second ingredient, of course, is you need some stabilization in the Middle East. With the midterms now weeks away, uh, and campaigning in earnest, that looks like that could be the next domino to fall.“
- “So the market reached our levels on nominal and real yields. That’s simply too cheap for, um, where we are today. And it’s a good buying opportunity.”
3. A change that has worked GREAT!
So happy that they finally implemented the College Football Playoff! Before that, much of the regular season was almost boring. You saw good teams from outside your conference but there was no focus. Now every week there is a game that impacts the chances of a team to get in to the playoff. That is why every week has at least one fantastic game.
This week it was LSU vs. Ole Miss. Man, it was something. When it ended, you felt both teams were terrific and you realized what a phenomenal player Trinidad Chambliss is. And you left with serious respect for LSU. It was the worst setup for LSU & they played a thoroughly rev-up Ole Miss led by the supercool Trinidad. And they came close to winning.
What a season so far!
Send your feedback to editor.macroviewpoints@gmail.com Or @MacroViewpoints on X.
