Summary – A top-down review of interesting calls and comments made last week in Treasuries, monetary policy, economics, stocks, bonds & commodities. TAC is our acronym for Tweets, Articles, & Clips – our basic inputs for this article.
- Editor’s Note: In this series of articles, we include important or interesting Tweets, Articles, Video Clips with our comments. This is an article that expresses our personal opinions about comments made on Television, Tweeter, and in Print. It is NOT intended to provide any investment advice of any type whatsoever. No one should base any investing decisions or conclusions based on anything written in or inferred from this article. Macro Viewpoints & its affiliates expressly disclaim all liability in respect to actions taken based on any or all of the information in this article. Investing is a serious matter and all investment decisions should only be taken after a detailed discussion with your investment advisor and should be subject to your objectives, suitability requirements and risk tolerance.
1.”.. the Real Risk going out …“
All week we heard little on Fin TV except Jensen Huang & NVDA. Look at the numbers below to see what a sideline event it was last week, even considering Semiconductors or even more locally AMD & Broadcom. And the broad S&P, the Dow, NDX, SMH & even the leveraged SOXL rallied as if asking NVDA who?
So what was more important to markets? That was answered by Warren Pies of 3Fourteen Research in his conversation with CNBC’s Sara Eisen on Wednesday, November 11:
- “…. I think the Fed is the real risk going out to the intermediate term & the market is not priced for another 2+ hikes that are probably coming… as you move thru the funding process, you start seeing indigestion in the funding market … it does concern me … as we turn the calendar into next year and we start thinking about January, March hikes … if we get that seasonality next year … I think you could start seeing some real indigestion in the equity market … “
Last week we quoted veteran Jim Paulsen on the risk of Fed tightening:
- “.. we have one small piece of the economy, 14% of new-era economy that is booming and 86% of the economy that’s barely growing 1% …. they may follow with another tightening move but I think its the wrong move; those policies have lags 3-4 months into the future …. suggesting there could be a pretty big economic slowdown“
John Kolovos of Macro Risk Advisors was more blunt last week:
- “… the biggest macro risk is that financial conditions are still very, very tight; … with that chances of a market crash are very, very elevated… the market is forcing the Fed’s hand here to NOT hike; if they hike, it would be a disaster“
On the other hand, look what Ed Yardeni of Yardeni Research said last Tuesday, November 10, on CNBC:
- “I am a big picture guy and the big picture is showing the economy is doing great, the labor market is doing extremely well & as Sara pointed out we have an inflation problem … I was thinking that the Fed passed on raising 25 bps in October … we probably get 50 bps in December meeting & that’s increasingly likely ... “
Wow !!!! Does Yardeni know or even care what happened in the country just a week before his comments? On Tuesday, November 3, there was a revolt of sorts from the American people against lack of affordability, lack of adequately paying jobs & against an economy that seems to be mainly of the rich, for the rich & by the rich. The people did vote to try & get rid of “the economy by the rich“. But they are not going to get what they want unless they get rid of the “economy for the rich“.
You know what made us go “Double Wow!!!!!!!” was the silence of CNBC’s Carl Quintanilla at Yardeni’s description of the “doing great” US economy and the “doing extremely well” labor market. But we are not surprised. Yardeni was going “oh wow” about the economy on CNBC, a network presumably full of million-dollar plus salaried on-air talent. And what can you say about Signor Quintanilla? We still recall a fellow CNBC on-air talent speaking rhapsodically about Mr. Quintanilla’s NYC apartment. So we guess his annual compensation might be in excess of $10 million annually, a figure reportedly paid by CNBC to other Senior Anchors!
There is another commonality to the thinking of Yardeni-types & CNBC-Quintanilla-types. To them an economy is going great if the US Stock Market is near the all-time highs & labor market is doing extremely well even if hardly any jobs are being added.
Any other place that exhibits this anomaly?
- J.C. Parets@JC_ParetsX – 11-15 – New all-time high once again this week for the broadest measure of European equities. This is not evidence of risk aversion or any kind of weird bear market.
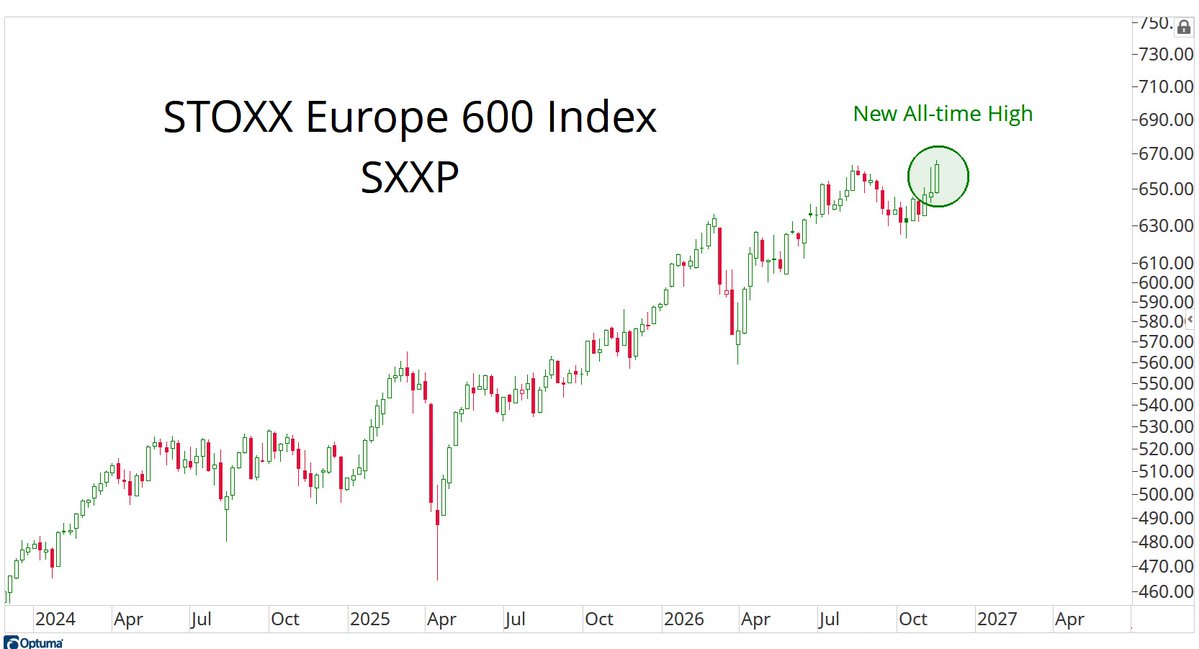
Triple Wow!!! So do European Yardenis publicly gloat about the European economy doing great & the European labor market doing extremely well? Why not? After all Europe is elite. So who cares about the European youth rioting in the streets & demanding the resignation of Macron, Meloni & other leaders? We guess neither European nor American Yardeni-CNBC-types do!
Allow us to imagine the following scenario:
- “Fed hikes interest rates by 50 bps creating more joblessness without reducing inflation; as anger builds, the one man who tried his hardest all thru 2026 gets to say he tried publicly & privately to get the Fed to cut rates. But the Republican House refused to put pressure on the Powell Fed. Had they listened to him, the economy might be in better shape with more jobs. So the House & Senate Republicans got thrown out”
Now he can voice his hope that the newly elected House & Senate leadership will work with him to compel the Fed to work for all of America & not only for the Financial Elite. And warn that if they don’t take advantage of their historic opportunity, they might suffer the same fate in 2028.
In a couple of months, President Trump might be in the right position to attack the Democratic Congressional leadership from the left, from the side of Americans caught in a vice created by Fed & the 2026 Republican leadership. And he might get serious support from Bernie Sanders, AOC, Mayor Mamdani and possibly even Senate-elect El-Sayed.
And he has a weapon in this fight – the intransigent behavior of Fed Chair Powell in 2026. Ask yourselves, will the new Democratic leadership find any common ground with ex-Chair Powell? This attack might just serve to scare the Fed into getting more on the side of 75% Americans who got squeezed by the Fed in 2026. And, if successful, President Trump could promise to ACT on behalf of the majority of Americans. The other weapon in this fight might be the million dollar plus compensation of gloating Fin TV on-air “talent” while bright, young Americans seek desperately to find jobs that pay a living wage.
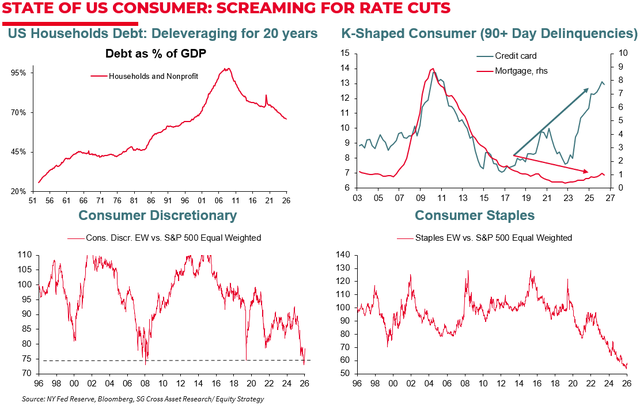
Look at the picture below & ask whether you are on the side of the majority of Americans who want the Fed to cut rates or the Yardeni-CNBC type financial aristocrats who want the Fed to raise rates?
We are simple folks & have been pro-sense and sensibility. But, frankly speaking, the sheer tone-deaf arrogance of Yardeni on CNBC & unopposed by CNBC’s Quintanilla made us angry & able to understand why Europeans are tearing down fancy monuments & palaces.
Vive la Egalite, Vive la Financial Revolution
Thank you Signor Yardeni & CNBC for making us feel 20-something young again!
2. Markets Last week
2.1 US Indices:
- VIX down 24.7%; Dow up 2.1%; SPX up 2.5%; RSP up 2.4%; NDX up 3.5%; RUT up 1.3%; MDY up 2.3%; XLU up 2.1%; SMH up 4.9%; SOXL up 26.9%; NVDA down 12.8%
A Friday view:
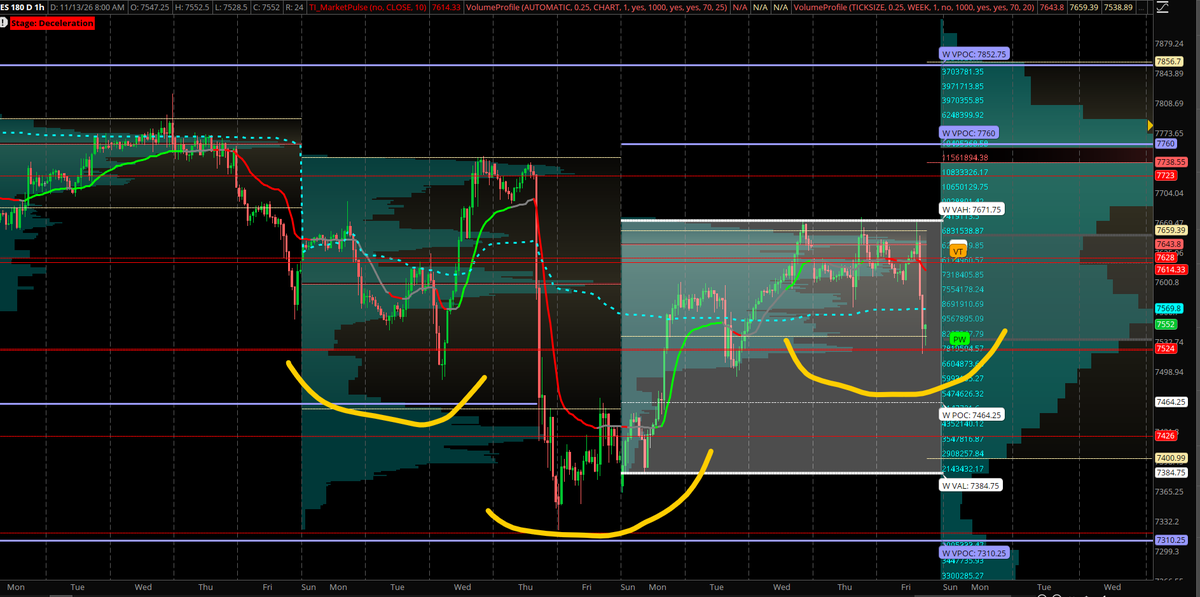
- Jason@3PeaksTrading – 11-13 – Inverted H&S bottom forming if this 7500 area holds..Remember the market is UP FOR THE WEEK so far.. and this market breadth is not bad today
Earlier in the week:
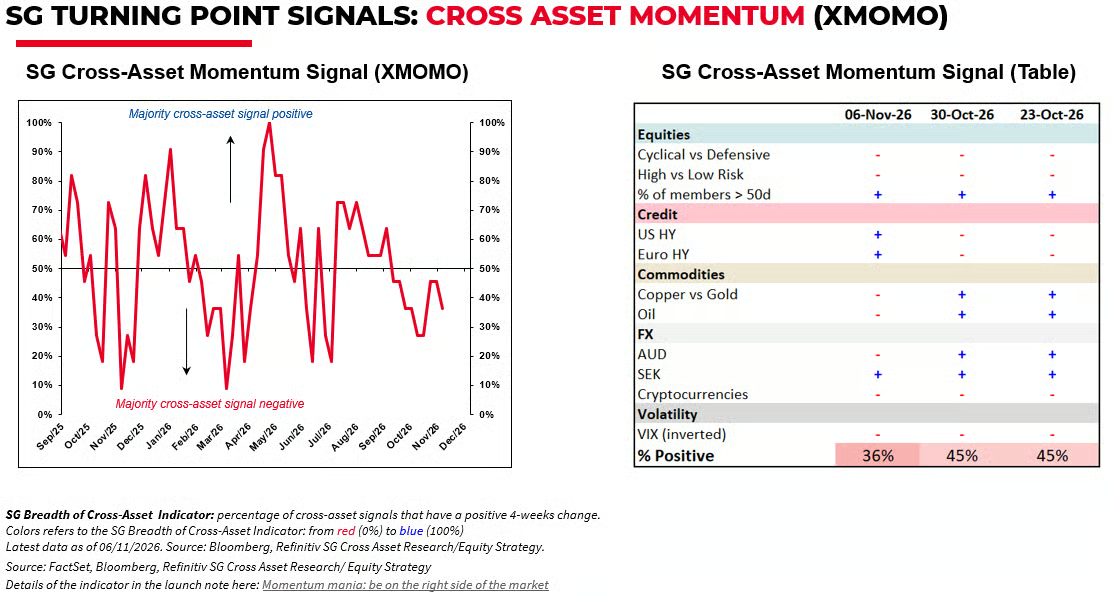
- Daily Chartbook – SocGen 3. Cross-asset momentum. “Risk-off is getting old. SG XMOMO is at 36%, cautious for a 10th week. Only the 2022 Fed hiking cycle produced a longer risk-off signal, at 11 weeks. We may be getting closer to the turn.”
2.2 MAGs:
- AAPL up 4.1%; AMZN up 2.8%; GOOGL up 3.9%; META up 5.2%; MSFT down 1.3%; NFLX down 2%; SMH up 4.9%; SOXL up 26.9%; AVGO up 18.2%; AMD up 18.9%; NVDA down 12.8%; MU up 12.8%; SNDK up 6%; IBM up 87 bps; IGV up 2.3%; CRM up 2%; PANW up 2.7%; NOW up 27 bps; PLTR up 4.7%;
Last week was NOT an NVDA-event despite the attention to it. Just look at the performance of AVGO, AMD & Semis in general.
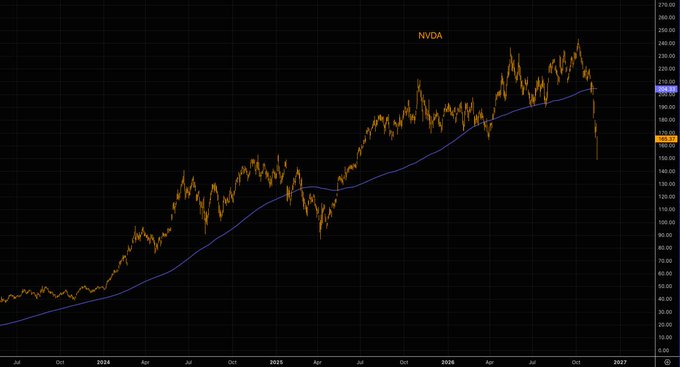
- The Market Ear@themarketear – 11-12 – NVDA was down nearly 40% from its October highs at today’s lows. Almost 30% below its 200-day MA. The last time we saw a washout this extreme? Liberation Day. Now comes Nvidia’s Steve Jobs moment.
A broader comment:
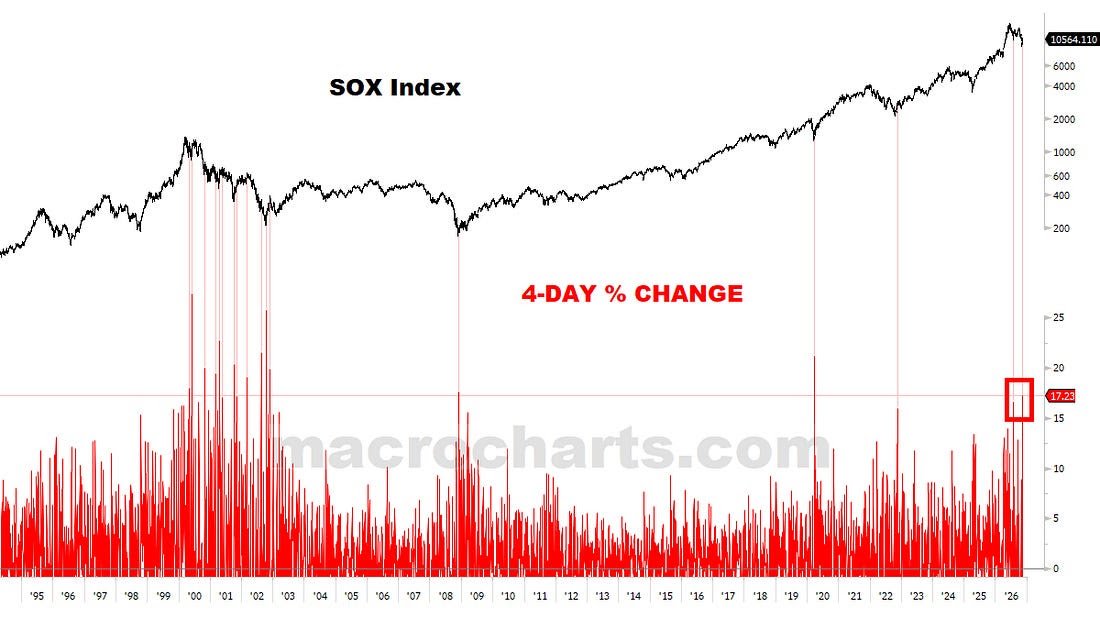
- Ryan Detrick, CMT@RyanDetrick – Buying thrust in the $SOX? Best 4-day rally since the Covid lows. Moves like this more often than not aren’t ‘just bear market rallies’, but a signal for a major change in trend. Great chart from @MacroCharts in his note this morning.
An even broader view:
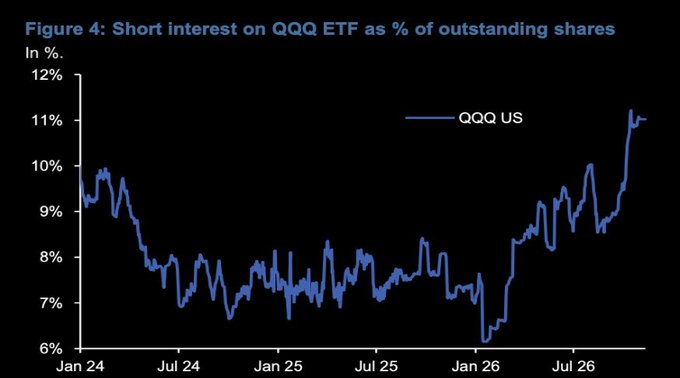
- The Market Ear@themarketear – 11-12 – QQQ shorts at their highest since 2023. Hedge funds underexposed. JPM sees the setup for the next AI squeeze.
2.3 Key Financials:
- BAC up 3.2%; C up 4.2%; GS up 5.9%; JPM up 3.5%; KRE up 75 bps; EUFN up 3.1%; SCHW up 1.6%; APO up 5.8%; BX up 58 bps; KKR up 1.6%; XHB down 22 bps; ITB down 2.6%; NAIL down 8.4%;
2.4 – Dollar & Metals
- UUP up 1.3%; DXY up 1.1%; Gold down 4.8%; GDX down 6.8%; Silver down 6.1%; Copper down 3%; CLF up 10.4%; FCX down 30 bps; MOS down 4.1%; Oil down 2.1%; Brent down 2.1%; OIH up 5.5%; XLE up 5.4%; PBR down 1%;
A Friday view:
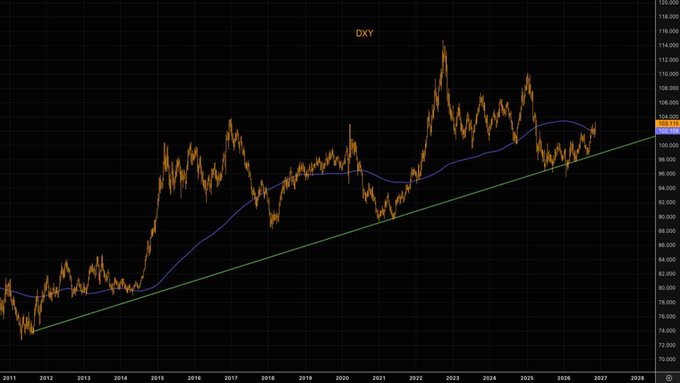
- The Market Ear@themarketear – 11-13 – Remember when everyone was calling for the death of the dollar? DXY just reclaimed its 200-week moving average. The euro can’t catch a bid.
2.5 – International Stocks:
- EEM up 2.7%; EMXC up 4.8%; FXI down 4.2%; KWEB down 7.8%; BABA down 13.8%; EWZ up 75 bps; EWY up 4.2%; EWJ up 4%; EWG up 3.2%; INDA up 1.1%; INDY up 22 bps; EPI up 1.6%; SMIN up 2.8%; IBN up 1.9%; HDB up 2.8%;
Early in the week:
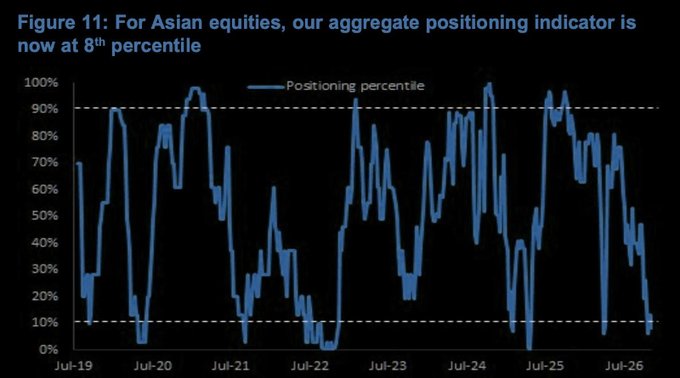
- The Market Ear@themarketear – 11-10 – “Everybody out.” JPM’s Asian equity positioning indicator has plunged to the 8th percentile. Historically, levels like these have marked major market bottoms.
2.6 Treasuries & Interest Rates
- 30-year Treasury yield up 21.6 bps on the week; 20-yr yield up 23.7 bps; 10-yr up 29.9 bps; 7-yr yield up 32.2 bps; 5-yr yield up 34 bps; 3-yr yield up 34.8 bps; 2-yr yield up 36 bps; 1-yr up 30.8 bps;
- TLT down 3.1%; EDV down 4.5%; ZROZ down 5%; TMF down 9.3%; HYG down 38 bps; JNK down 41 bps; EMB down 90 bps;
What will the Fed do?
But what about the strong CPI report that made Waller speak of possibly 50 bps hike? David Rosenberg was less emotional & more data-dependent in his Rosenberg Recap.
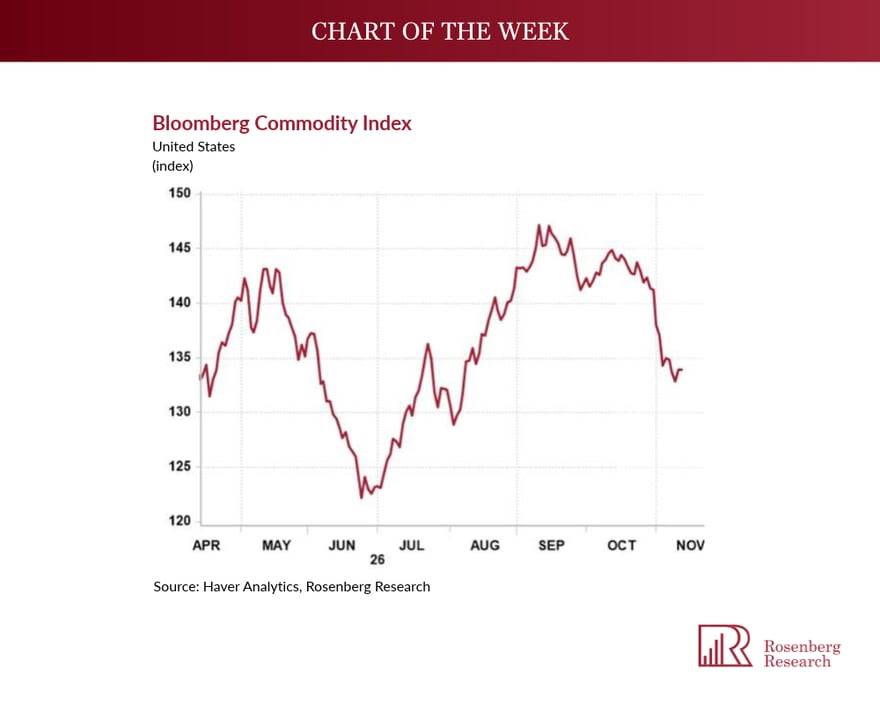
- The CPI data are a lagging indicator, and that is what the Fed is chasing. In real time, the commodity sector is rolling over. Resource prices, in aggregate, have fallen more than -9% from the nearby peak. Gasoline prices remain elevated in level terms but have reversed nearly -30% from the wartime peak. Diesel is down -22% from its punishing peak and has retraced half of the upmove. This is good news for relief in terms of transportation costs (and foodstuffs). Indeed, the Baltic Dry Index has matched this decline from the highs. Base metals have rolled over by -10%.
- Food featured heavily in the CPI report, but in the commodity pits, the grains complex has collapsed by -17% from the nearby peak. Soybeans, wheat, and corn have all rolled over in a major way. Beef prices are about to come way down — livestock prices are down -20%. Hogs are down -40%.
- … the 10-year TIPS breakevens fell for the fifth time in a row — the lowest since late July, when the nominal yield was 4.61%.
Below is a discussion of news that reportedly broke on November 14. We are highly unfamiliar with the business entities discussed and have no knowledge of the transactions mentioned below. The topic is important and the news seems important to the discussion about whether the Fed needs to hike rates or cut rates. We would be sincerely thankful to get any informed feedback from readers.
Send your feedback to editor.macroviewpoints@gmail.com Or @MacroViewpoints on X.
