Summary – A top-down review of interesting calls and comments made last week in Treasuries, monetary policy, economics, stocks, bonds & commodities. TAC is our acronym for Tweets, Articles, & Clips – our basic inputs for this article.
- Editor’s Note: In this series of articles, we include important or interesting Tweets, Articles, Video Clips with our comments. This is an article that expresses our personal opinions about comments made on Television, Tweeter, and in Print. It is NOT intended to provide any investment advice of any type whatsoever. No one should base any investing decisions or conclusions based on anything written in or inferred from this article. Macro Viewpoints & its affiliates expressly disclaim all liability in respect to actions taken based on any or all of the information in this article. Investing is a serious matter and all investment decisions should only be taken after a detailed discussion with your investment advisor and should be subject to your objectives, suitability requirements and risk tolerance.
1.A Friday in October
Around 10:00 am on Friday (October 16), the Dow had rallied to 52,550. Then strangely & slowly it began giving up the gains & went negative just after noon. It closed down on Friday at just above 52,000. Ryan Detrick wrote about this on Sunday morning:
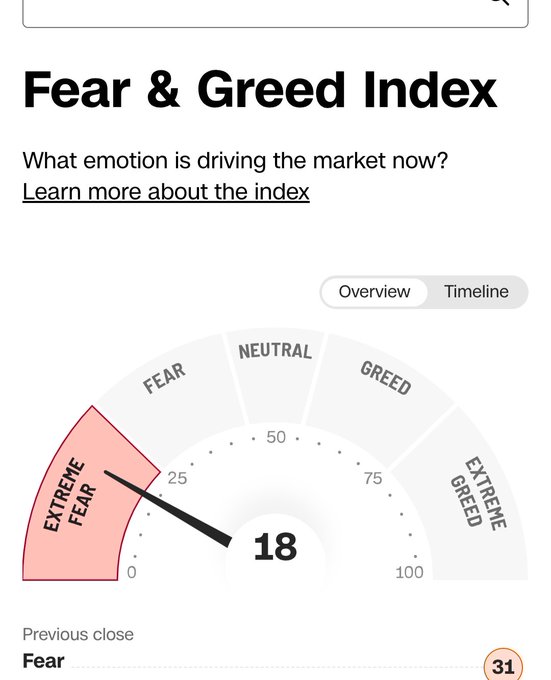
- Ryan Detrick, CMT@RyanDetrick – Sun 10-18 – Historically, you tend to see late October major lows in midterm years. Fear is spiking in major ways. Huge jumps in put volume on Friday. $SPY 3rd highest put volume ever and $QQQ 2nd most ever.
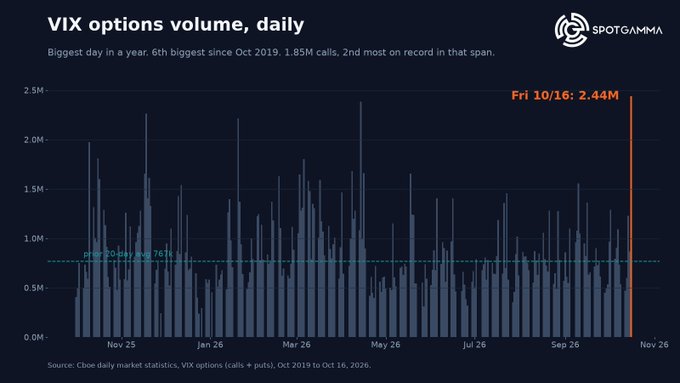
As SpotGamma posted on Saturday, the story was Volatility.
- SpotGamma@spotgamma – 10-17 – VIX options traded 2.44M contracts Friday, the most in a year and 3x average. 1.85M of that was calls. 1.2M of that was tied to 10/21 exp.
To put in simple language,
- The Market Ear@themarketear – 10-17 – Somebody is in serious trouble. Record tech selling. VIX exploding. Volatility positioning getting crushed. Friday’s carnage has all the hallmarks of a major forced liquidation. The charts are wild.
Did anybody mention AI or Hyperscalar?
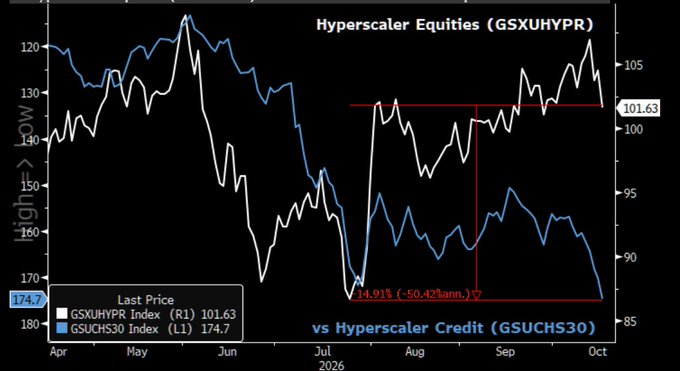
- The Market Ear@themarketear – 10-17 – AI Hyperscaler Equities were 15% lower the last time spreads were this wide. https://zerohedge.com/the-market-ear/funeral-century-wall-street-burying-ai-trade
Any comment re Hyperscalar CDS?
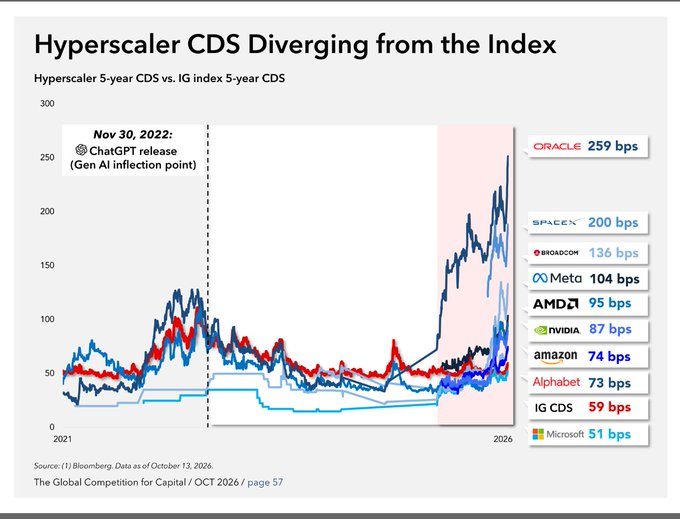
- Mike Zaccardi, CFA, CMT 🍖@MikeZaccardi – 10-18 – Hyperscaler CDS spreads bear watching into 2027 (and the neoclouds) MUFG
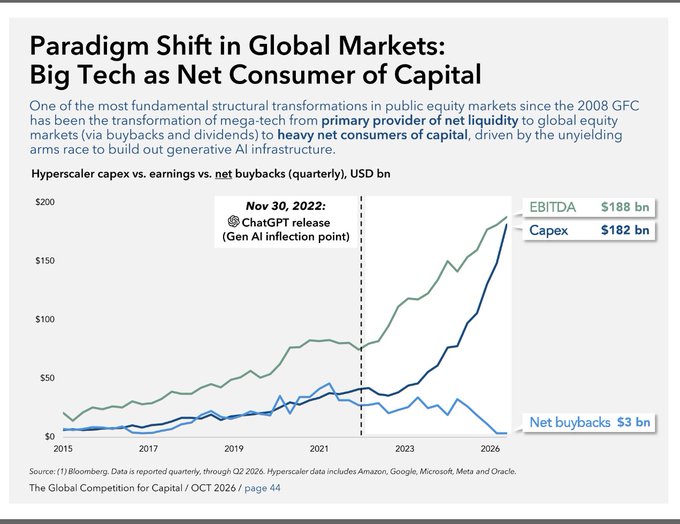
A new AI era!
- Mike Zaccardi, CFA, CMT 🍖@MikeZaccardi 10-18 – The new AI era… parabolic capes, declining net buybacks (MUFG)
What about Neoclouds?
- Thomas Thornton@TommyThornton – Fri 10-16 – GS Neocloud basket -48% off high
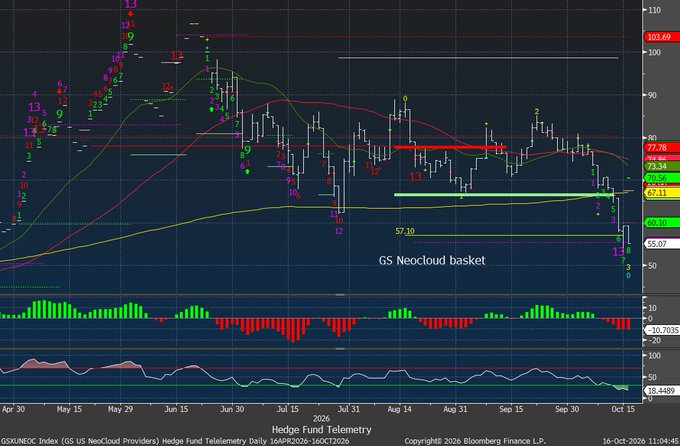
No wonder a few had already begun calling Signor Amodei for postponing the Anthropic IPO!
But one sign that NDX might possibly be near a decent level!
- The Market Ear@themarketear – Fri 10-16 – The P/E of the NDX is back to ~21x – the lows since the AI cycle kicked off in 2023. Is that also a quadruple bottom…?
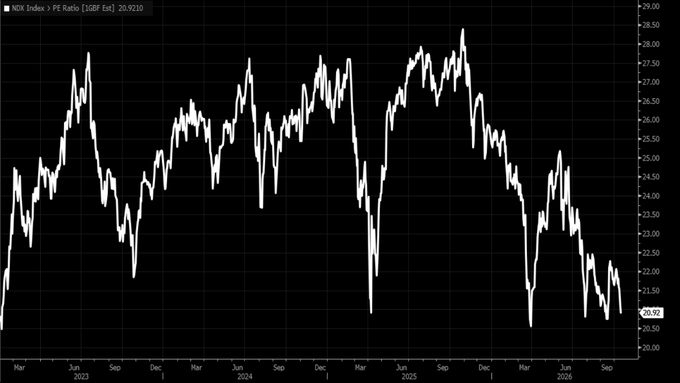
Now that would be kinda our thought but for memories of other mid-October fear-based selloffs and about not being brave ahead of October OpEx. And there is no shortage of alarming speculation by supposedly informed sources about what might happen in 7-10 days.
As a smart and courageous strategist was quoted on CNBC on Thursday:
- “We continue to believe that equities are going to climb the wall of worry & breakout to the upside well before midterms“
He is correct in saying “Semis have great balance sheets” and his argument that “rates have now started to come off” is also valid. His timing might have been either a little off or courageously great if Semis & stocks bounce up next week as they did after a few months ago when Citadel stepped up to buy a portfolio everybody was running from. After all situational awareness is usually clear after people become aware that the situation has been cleared.
So let us hope that the situation stabilizes & becomes inviting post OpEx on October 17.
Allow us to close this section after sharing a true but funny comment we found this morning:
- Markets & Mayhem@Mayhem4Markets – 10-18 9:29 am – And now these same people have Black Monday trending. You cannot make this shit up. 🤣
And who are “these same people”?
- Markets & Mayhem@Mayhem4Markets – 10-17 – The “same people that wanted 24/7 stock market trading” are panicking about weekend price action.
2. Markets Last Week
2.1 US Indices:
- VIX up 36% to 20.12; Dow up 67 bps; SPX down 2%; RSP up 49 bps; NDX down 5.5%; RUT down 3.1%; MDY down 1.5%; XLU up 1.9%; SMH down 10.5%; SOXL down 33%; NVDA down 6.6%.
2.2 MAGs:
- AAPL up 2%; AMZN down 4.7%; GOOGL down 3.2%; META down 1.3%; MSFT down 1.1%; NFLX up 33 bps; SMH down 10.5%; SOXL down 33%; NVDA down 6.6%; MU down 14.6%; SNDK down 17.9%; IBM up 2%; IGV down 7.4%; CRM up 5.1%; PANW down 18.3%; NOW up 79 bps; PLTR down 11%;
As we noted above, the stock advance turned negative just after noon on Friday. That was happening was while Warren Pies was on CNBC speaking to Carl Quintanilla & Sara Eisen. Watch the clip below to notice that all three were utterly oblivious to the debacle then unfolding in the stock market. And if you have followed Mr. Pies, you will know that the Fed is the main impediment that he sees:
- “We are over-weight; we have been so since Fed hiked rates; …. you have to take account of that & be appropriately paranoid – we looked around, we sensed nervousness from our clients. But when I really dig into concerns this week, I don’t see why anything that is going to derail the bull market …. we are still on track for probably breaking thru 8,000 in S&P before the year is over & I want to maintain an equity over-weight. I do think tech will ultimately lead that bull run; …”
- “… this is a push-pull market; it expresses itself in breadth concerns … these bouts of weak breadth, market nervousness really occurred since the AI period; … the real support is earnings story … 20% of stocks above the 50-day – that’s a very good entry point … rates cool off & market broadening – that’s exactly what you want to see … let tech catch its breadth & take back leadership … “
2.3 Key Financials:
- BAC down 5.7%; C down 4.2%; GS down 1.6%; JPM up 2%; KRE up 1.2%; EUFN up 91 bps; SCHW down 4.9%; APO down 6.6%; BX down 6.7%; KKR down 5.2%; XHB up 15 bps; ITB up 1.9%; NAIL up 5.2%;
2.4 – Dollar & Metals
- UUP down 34 bps; DXY down 43 bps; Gold down 73 bps; GDX down 1.8%; Silver down 6.2%; Copper down 2%; CLF down 6.6%; FCX down 5.6%; MOS up 43 bps; Oil up 11.1%; Brent up 5.3%; OIH down 1.7%; XLE up 4.9%; PBR up 2.8%;
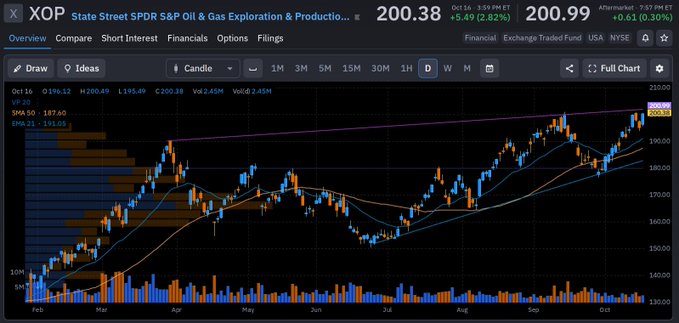
- Markets & Mayhem@Mayhem4Markets – 10-18- $XOP – could be on the verge of a major move higher 🤔
2.5 – International Stocks:
- EEM down 5.9%; EMXC down 6.8%; FXI down 1.2%; KWEB down 2.1%; BABA down 2%; EWZ down 3.9%; EWY down 15.1%; EWJ down 3.1%; EWG up 1.5%; INDA up 3.5%; INDY up 4.1%; EPI up 3.6%; SMIN up 3%; IBN up 7.5%; HDB up 7%;
Korea just can’t catch a break:
- Scott Brown, CMT@scottcharts – 10-16 – Worst week for the Korea KOSPI (-13.3%) since 2008 as it breaks below the 40-week moving average for the first time since its parabolic advance began
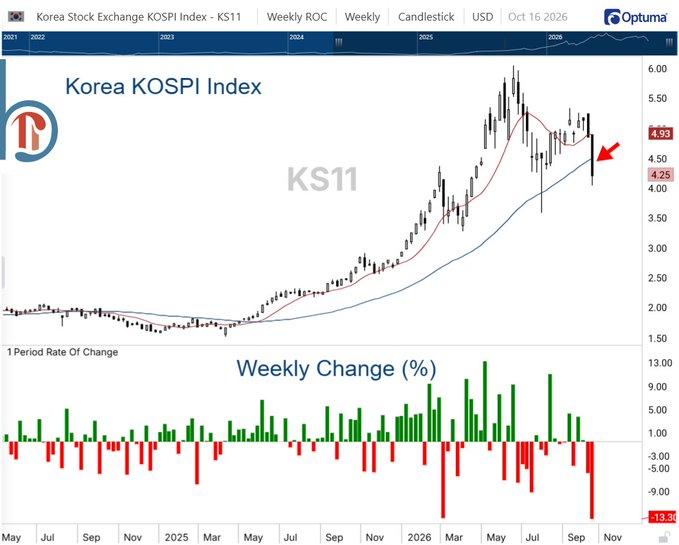
The above is awful but well-known. Hasn’t the Indian market been in a similar “who cares” position all year?
- The Market Ear@themarketear – 10-16 – Everyone is watching the Asian tech meltdown. Almost nobody is watching what’s happening in India.
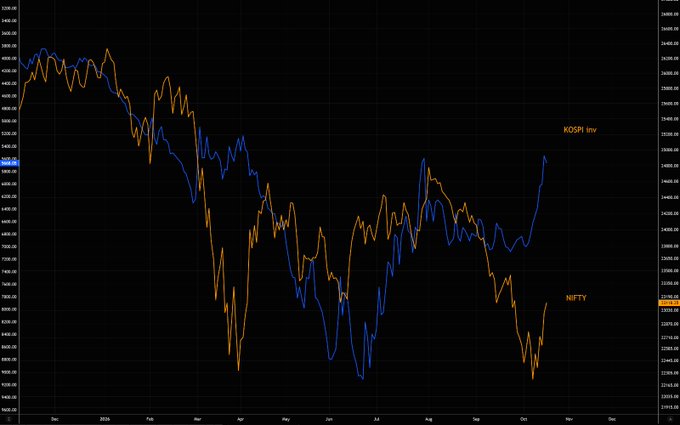
In fact, no one in US Financial Media is watching or even noticing what is going on right now between USA & India. While they have paid attention to the intense words used in the US against India, especially the Russia-India relationship in oil, and while some Fin TV anchors publicize their knowledge of global Energy Markets on air, these folks have not even shown basic knowledge of India’s global position in Oil.
In fact, we have heard nothing about the 6-day visit of Secretary of State Rubio to India beginning on October 20. Published sources say he is NOT visiting Delhi, India’s capital, during this visit. Hmmm? So what is the purpose of this visit? Does it have anything to do with what India has become? What has it become, inquiring minds in Fin TV might ask. What might they learn from the clip below?
- “India has become the 2nd largest diesel supplier in the world with half of India’s diesel shipments heading to Europe. The Reliance Jamnagar refinery is the largest single-site refinery anywhere in the World while India has also acquired nearly 50% stakes in Russian oil refineries for unlimited oil supply.”
Now consider, in this context, the destruction of oil facilities you see in virtually all of the middle east. That makes us wonder what happens to refinery demand once the hostilities end or even simmer down. That may take awhile given what smart (assumed smart?) US “expert” voices know about either Saudi Arabia or Yemen or both. We read that Egypt is getting ready to send troops to fight AnsarAllah. Have they forgotten what happened to the strong Egyptian Army Nasser had sent to Ethiopia to fight the same folks? From what we read, fighting these Yemenis in their land essentially “broke” the Egyptian Army and Nasser recalled them. That was a year or so before the Six-day war with Israel in 1967.
And what is happening to the Mecca accord re “Islamic NATO”? Erdogan has wisely declared that pact is entirely defensive & so Turkish Army will NOT go into Yemen. But Na-Pakistan has sent troops to Saudi-Yemen to fight AnsarAllah. Reportedly, 47 Napaki troops have surrendered already to the Houthis & further fighting by Napaki army has ceased.
Ask what madness inspired Napaki Army to go against AnsarAllah in Yemen when two of its martial races in two provinces are now in active insurgency against the Napaki Army! We mean the Gilgit-Baltistan province in the north (bordering China & India) and the yellow Khyber-Pakhtunkhawa bordering Afghanistan are now in virtual war with predominantly Panjabi army.
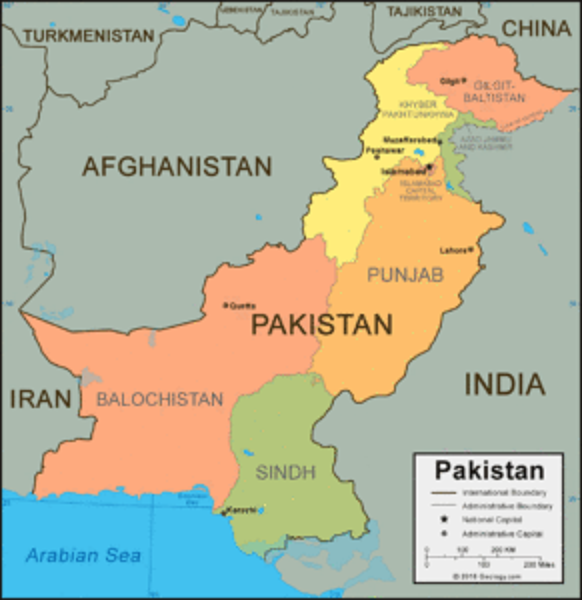
The above conflicts are not new but they are more intense with Afghanistan, Iran & even China now backing the Houthis against the Napaki army. And Russia is helping the Afghan army with some supplies & training. In case you didn’t know, Russia has now a pact with Afghanistan driven by the need for road corridors between Russia & India thru Central Asia & Afghanistan.
Finally the above Napaki stuff is mainly local and far less important for world markets than the future of the Saudi “Royal” family. And what we hear from ex-military sources in the US is outright scary. Below are two examples:
- THE COLLAPSE OF SAUDI ROYAL FAMILY – Col. Larry Wilkerson, former chief of staff to Secretary Colin Powell – 8:47 minutes – Oct 17, 2026
- Saudi Arabia Is Collapsing Under the Weight of the Yemen War – Scott Ritter – former US Intelligence Officer – 16 minutes – Oct 12, 2026
In the midst of all this & the appalling violence in major French cities, where is the French army? Macron has, reportedly just sent French troops to Saudi Arabia. And guess what the UK Army Chief and another Maj General Tim Cross have demanded? Sacrifices from UK people for Britain’s war in Ukraine.
Given this madness in Europe’s leaders, why aren’t the European markets down far more? Because European indices, as we understand, are made up of European Multinationals that are mainly global. And European leaders can be as stupid as they like because their mess doesn’t affect major commodities or anything vital.
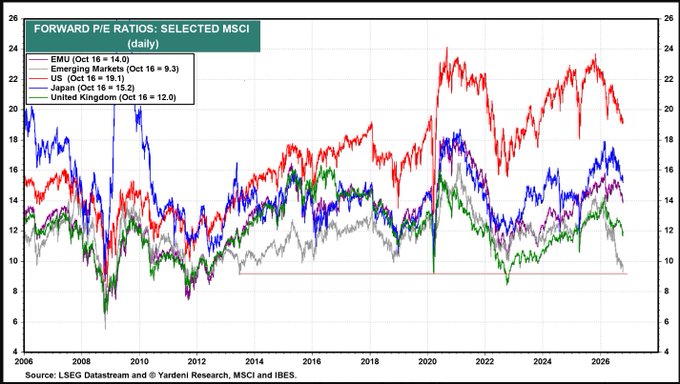
Given all that, what is one good thing about International Stocks?
- Mike Zaccardi, CFA, CMT 🍖@MikeZaccardi – Emerging Market P/E is now the lowest in 13 years @yardeni 9.3x $EEM
2.6 Treasuries & Interest Rates
- 30-year Treasury yield down 16.6 bps on the week; 20-yr yield down 16.9 bps; 10-yr down 15.9 bps; 7-yr yield down 15.4 bps; 5-yr yield down 13.8 bps; 3-yr yield down 11.1 bps; 2-yr yield down 7 bps; 1-yr down 2.1 bps;
- TLT up 2.6%; EDV up 4.3%; ZROZ up 4.8%; TMF up 7.9%; HYG down 48 bps; JNK down 59 bps; EMB up 38 bps;
Kudos to BlackRock for their strategy call this past week about Upgrading Short-Term Treasuries and Downgrading U.S. Equities to neutral. It might also help if interested people watch the 15-minute clip below of BlackRock’s Rick Rieder explaining his views in detail on Bloomberg Surveillance. The clip is after the quote below from BlackRock:
- “We upgrade U.S. Treasuries, preferring short-term bonds, as higher yields improve potential returns, partly funded by downgrading U.S. equities to neutral. .. Higher yields and potentially excessive Fed tightening expectations create room to unwind our U.S. Treasury underweight – a mainstay for most of the last six years. We upgrade Treasuries, favoring short-term bonds. In turn, we take profits: downgrading U.S. equities to neutral to manage potential volatility around the AI buildout and trimming our Japanese government bond (JGB) underweight. We retain our conviction in AI fundamentals and preference for AI within U.S. equities.“
The clip of Rick Rieder from Bloomberg Surveillance:
How smart was CNBC last week in bringing on 5 different market professionals who recommended Buying Short-Term Treasuries, a couple of them who were steadfastly against Buying Treasuries for awhile! Hopefully CNBC would keep this section of their collective minds open at least for a bit more.
But none of them spoke about was positioning?
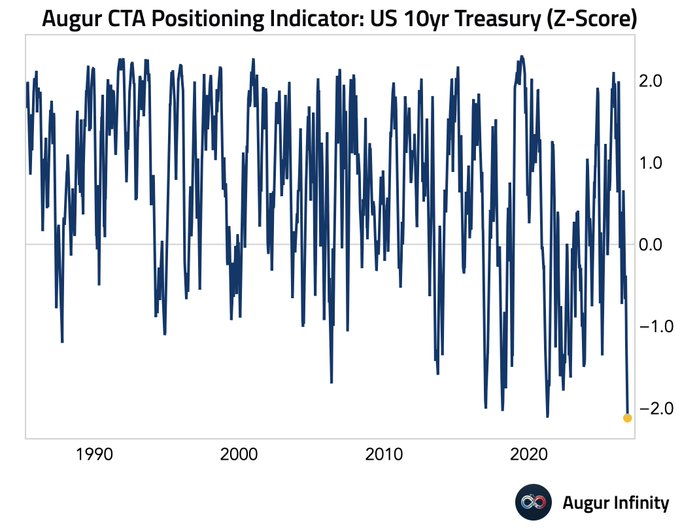
- The Market Ear@themarketear – 10-13 – Something is brewing in bonds. CTAs are heavily short. Treasury yields are reversing. MOVE just broke below 100. The next big squeeze could be in Treasuries.
Then on Thursday we saw:
- Augur Infinity@AugurInfinity – 10-15 – Our CTA positioning indicator for US Treasuries reached a record low ahead of the rally.
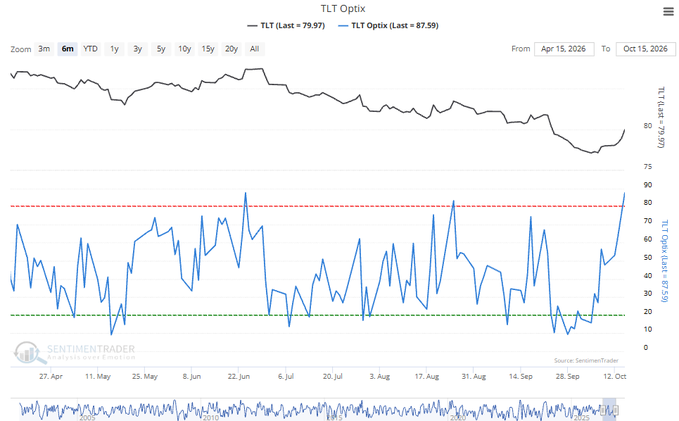
But sentiment on long-duration Treasuries surged more than the price action according to those who track sentiment:
- SentimenTrader@sentimentrader – 10-16 – Long-term Treasury sentiment has swung from one extreme to the other. Oct. 15: $TLT sentiment surged to 87.59, up from near 10 in late September. Yet $TLT‘s price rebound has been far more modest. https://sentimentrader.com/light-data-api?utm_source=twitter&utm_medium=content&utm_campaign=lightapi&utm_content=unusual_20261016_tltoptix
Finally, what we love about College Football!
- Sports Illustrated@SInow – WHAT A DAY IN COLLEGE FOOTBALL 🤯
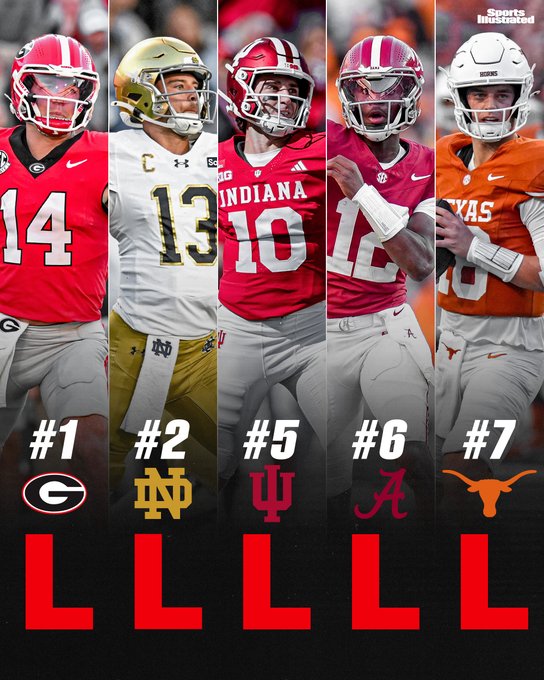
A great interception by Miami in the end zone preserved their unbeaten status. Surely an ecstatic Ken Griffin would put on another proof of his situational awareness like the last time! Frankly, the Miami Hurricanes were robbed because they should have moved up from No.3 to No.1. Yes, we loved watching BYU but they also won the way Miami won – courtesy of one final defensive play. So why was BYU moved up from No. 8 to No. 1 over Miami? Guess the old fogies still hate the old Miami Hurricanes!
Send your feedback to editor.macroviewpoints@gmail.com Or @MacroViewpoints on X.
