Summary – A top-down review of interesting calls and comments made last week in Treasuries, monetary policy, economics, stocks, bonds & commodities. TAC is our acronym for Tweets, Articles, & Clips – our basic inputs for this article.
- Editor’s Note: In this series of articles, we include important or interesting Tweets, Articles, Video Clips with our comments. This is an article that expresses our personal opinions about comments made on Television, Tweeter, and in Print. It is NOT intended to provide any investment advice of any type whatsoever. No one should base any investing decisions or conclusions based on anything written in or inferred from this article. Macro Viewpoints & its affiliates expressly disclaim all liability in respect to actions taken based on any or all of the information in this article. Investing is a serious matter and all investment decisions should only be taken after a detailed discussion with your investment advisor and should be subject to your objectives, suitability requirements and risk tolerance.
1. Did we see a peak of sorts?
To begin with, what is our preference in peak in a market? Oil, we would answer. And that peak is dependent on events in Iran and in Saudi Arabia!
If Saudi oilfields are put out of commission by Ansar Allah (Houthis), then most bets will be off. By the way, as we heard in an overnight You-Tube clip from London, Saudi & its allies intervened in Yemen & toppled the previous government and the senior military leadership of the previous Yemeni government escaped into what became Houthi land (named after al-Houthi). In other words, the people running the “Houthi” campaign are senior military ex-leaders who thoroughly understand the Yemeni terrain & tribal structures. Secondly the Yemeni leadership that replaced them soon evolved into two factions, pro-Saudi and pro-Emirati (UAE). These two began fighting each other making it easier for Ansar Allah. The ultimate end to this conflict might be the removal of MBS from power & the rise of a military junta in Riyadh that can sensibly negotiate a de facto partition of Saudi Arabia.
What is happening right now in Yemen? According to Rory Johnston, a Toronto-based oil analyst and the founder of Commodity Context, an independent oil market research firm, as quoted by Zerohedge,
- “Saudi Arabia is driving the recovery. The kingdom’s crude exports averaged 5.28 million barrels a day during September’s first 23 days, the strongest pace since the conflict began, according to Bloomberg ship-tracking data. About 3.4 million barrels a day were loaded at Gulf ports, reversing the near-total retreat from those terminals earlier in the war.”
And,
A bigger & thornier problem is Iran. That war cannot end on terms insulting to the Trump Administration and, in any case, might be impossible to end until the mid-terms. All we can hope for is a tone-down of rhetoric, if possible. This week’s most comical development is Macron’s announcement about sending French troops to Saudi Arabia after also promising sending French troops to Ukraine.
Another peak of sorts brings us to a potentially climactic action (potentially) culminating on Thursday, September 24:
- The Market Ear@themarketear – 9-25- Someone big looked like they were getting stopped out in bonds on Thursday. MOVE is surging. VIX is still asleep. This gap is getting hard to ignore.

- Mike Zaccardi, CFA, CMT – @MikeZaccardi – 2s30s wild ride this week.. from 47bps at the Weds low to 64bps today @CNBC

- Mike Zaccardi, CFA, CMT 🍖 – @MikeZaccardi -Fri 9-25 – Good bookends to the week… massive Monday rally, solid ascent today @koyfincharts
- The Market Ear@themarketear – Credit is warning. Bond vol is exploding. Equities refuse to care. What happens if NDX finally takes out the range highs? There is only vacuum above.
Is “vacuum” another word for equity positioning?
- Mike Zaccardi, CFA, CMT @MikeZaccardi – 9-26 – GS US Equity Sentiment Indicator of investor positioning is not aggressive as we head into Q4 of the midterm year (which is historically very strong) (declined to -0.9, matching the lows reached in March)

2. Markets Last Week
2.1 US Indices:
- VIX up 5.3% to 15.60; Dow up 28 bps; SPX up 1.2%; RSP down 56 bps; NDX up 3.3%; RUT down 77 bps; MDY down 12 bps; XLU down 3.9%; SMH up 5.9%; SOXL up 22.5%; NVDA up 1.3%.
Positive signals for this coming week?
- Mike Zaccardi, CFA, CMT 🍖 @MikeZaccardi – Fri 9-25 – $VIX dumps back under 15

- Larry Tentarelli, Blue Chip Daily @bluechipdaily – 9-26 – $NDX made a new record weekly closing high, over 4 rising weekly MAs + multiple weekly MA crosses. Are all bullish trend signals.

He pointed out that $QQQ has behaved similarly.
If rates cool down, then what might benefit?
- Mike Zaccardi, CFA, CMT 🍖@MikeZaccardi – $XLU Utilities worst RSI in 3 years; Almost a 20% drawdown… price lowest since April 2025

But could $XLU be going for a hammer that needs a microscope to see?
- Mike Zaccardi, CFA, CMT 🍖@MikeZaccardi – $XLU could be going for a bullish hammer

Tom McClellan had an interesting comment on his site this week:
- “The Ratio-Adjusted Summation Index (RASI) for the NYSE is down to -522 and still falling. This is low enough to mark a decent end point for an ordinary market correction. Yes, it can go lower than this, especially in a determined bear market. But a low reading like this in a long term uptrend is a nice thing to see. ….When the RASI turns up, the classic version of the McClellan Summation Index will turn up at the same time. A good bullish move can take the RASI from current levels to above the +500 level in a single run. Failure of the RASI to make it back above +500 would identify possible problems with the price advance.”

2.2 MAG 7:
- AAPL up 1.5%; AMZN down 1.6%; GOOGL down 1.6%; META up 12.9%; MSFT up 4.5%; NFLX down 90 bps; SMH up 5.9%; SOXL up 22.5%; NVDA up 1.3%; MU up 6.5%; SNDK down 78 bps; IBM down 1.8%; IGV up 1.6%; CRM down 1.6%; PANW up 3.1%; NOW up 11 bps; PLTR up 6.8%;
Does the liftoff go higher this week or falls back?
- Mike Zaccardi, CFA, CMT 🍖@MikeZaccardi – Mag 7 $MAGS liftoff to record highs.. More from me on @stockcharts : https://articles.stockcharts.com/article/mag-7-breakout-watch-heres-where-the-glamour-stocks-could-go/

But how did MTUM behave vs. SPY during the week?
- Mike Zaccardi, CFA, CMT 🍖@MikeZaccardi – Sep 25 – $MTUM vs $SPY – momentum factor up each day this week… don’t call it a comeback..

If you think that is impressive, how about up for 4 straight weeks?
- Mike Zaccardi, CFA, CMT 🍖@MikeZaccardi – $SMH – up 4 straight weeks

Into these expectations of joyous future returns, stepped Ohsung Kwon, Chief Strategist at Wells Fargo and he does say as he did with CNBC’s Mike Santoli that “2027 is locked; everything is going to be amazing next year“. Then he added:
- “its 2028 & beyond; … it will become increasingly difficult for hyperscalars to justify another record years after 2027; How high does AI have to get to justify the cap-ex cycle? that is going to around $1.4 trillion by 2028…. meaning $9,000/- per year per worker; …. say we get there somehow;… to imagine another trillion dollar capex in 2028!!!”
Then he moved to fair equity allocation:
- “there is a huge gap in allocation to equities & bonds; – 70% allocation to stocks & 28% to bonds; that’s the highest since 1969; we are at fair equity allocation of 60% stocks for next 5 years with 5% rates;…”
What about the earnings cycle? He said:
- “by next year, we are going to have one of the strongest eps cycles in history, only surpassed by 1950s bull run and 2027 will be 42% above our normalized eps“
That is why he has downgraded his S&P target to 7700-7950, by year-end & he is leaning more towards health-care.
2.3 Key Financials:
- BAC down 1.8%; C up 1.9%; GS down 70 bps; JPM down 1.9%; KRE down 1.7%; EUFN down 32 bps; SCHW down 5.9%; APO down 3.4%; BX down 5.2%; KKR down 2.2%; XHB up 2%; ITB up 2.3%; NAIL up 5.8%;
Last week, John Kolovos of Macro Risk Advisors alluded to his credit spreads model showing off some concerns. He focused last week on a key sector for his worries:
- John Kolovos, CMT, CFA@John_Kolovos – – Still seeing the best charts in Tech and Healthcare/Biotech today. Plenty of names there are either breaking out, accelerating, or just digesting gains near the highs. Financials are the worrisome part, as they are acting heavy, and it is getting harder to dismiss as a few bad charts. If that group keeps breaking lower, it will be tougher for the S&P to push through and hold new highs in the near-term, even if Tech keeps doing its thing. Also seeing weakness in Comm Services, travel/leisure and parts of Industrials. Energy looks more mixed to me, with a few names sitting on support rather than breaking down outright. $XLF $XLK $IBB @CMTAssociation

- Mike Zaccardi, CFA, CMT 🍖@MikeZaccardi – $XLF poised for a 3rd week of losses; I took a crack at the bank et al on @stockcharts this week too: https://articles.stockcharts.com/article/meta-muse-meltdown-in-financials-is-xlf-selloff-a-buying-opportunity/

2.4 – Dollar & Metals
- UUP up 1.1%; DXY up 1.1%; Gold down 2.5%; GDX down 2.7%; Silver down 4.1%; Copper up 95 bps; CLF down 2.6%; FCX up 1.1%; MOS down 6%; Oil down 7.2%; Brent up 1.1%; OIH down 1.3%; XLE down 3.5%; PBR down 2.1%;
Well, if Oil stabilizes & heads down, what happens to big-cap oil stocks? We don’t know is our answer.
2.5 – International Stocks:
- EEM up 1.4%; EMXC up 1.9%; FXI down 1.1%; KWEB down 1%; BABA down 3.1%; EWZ down 1.9%; EWY up 3.2%; EWJ up 96 bps; EWG up 26 bps; INDA down 33 bps; INDY down 26 bps; EPI up 34 bps; SMIN down 10 bps; IBN down 82 bps; HDB down 65 bps;
Notice that EM etfs are up for countries that are farther away from Iran & Yemen. We guess these same ETFs might rally more if oil does settle down.
2.6 Treasuries & Interest Rates
- 30-year Treasury yield up 15.5 bps on the week; 20-yr yield up 16.6 bps; 10-yr up 15.2 bps; 7-yr yield up 13 bps; 5-yr yield up 11.3 bps; 3-yr yield up 8 bps; 2-yr yield up 8.7 bps; 1-yr up 5.7 bps;
- TLT down 2.3%; EDV down 3.8%; ZROZ down 3.7%; HYG down 85 bps; JNK down 99 bps; EMB down 1.3%:
What about TLT?
- Mike Zaccardi, CFA, CMT 🍖@MikeZaccardi – Sep 25 – $TLT big bearish engulfing on the weekly… volume not all that high..

Also,
- Mike Zaccardi, CFA, CMT 🍖@MikeZaccardi – Sep 26 – US Treasury buyer base is becoming more interest-rate sensitive… making those larger auctions all the more interesting Torsten at Apollo

Warren Pies of 3Fourteen Research focused this week on interest rates & said the 10-yr Treasury is now at fair-value between 5.1% & 5.2%. He expects one more rate hike followed by a hawkish bias. to him, this cycle is like the 1997 Fed cycle. He retains his last week’s thesis of Hyperscalars & Mega-Cap tech as leaders followed by Semis. He also thinks oil prices & volatility will be alleviated & become positive for the stock market.
3.3 OMG! CNBC woman host uses a “b” word to address a woman CEO guest!
Seriously, we have never seen or heard this in our multiple decades of watching CNBC shows. We are not experts in US insults but we are aware that the “b” term pronounced clearly as “bi*ch” is an offensive term used to insult a woman. We have mainly heard it used in NYC subway conversations laced with anger directed at the woman.
This week we heard its variant used by a CNBC Indian-American host directly at an Indian-American CEO of a national firm. And not just once but more than once right at the opening of the conversation. And you can see the CNBC Indian-American host smiling as she uses the term while the Indian-American CEO answers with a stoic, unsmiling facial expression.
The term actually was NOT the English term “Bi*ch” but the North-Indian term Kamini, a term that is described as:
- “Kamini (کَمِینی) …. means “mean, vulgar, ignoble, or base” As an Insult: It is often used as a derogatory or insulting term for a woman who is considered untrustworthy, low-minded, or acting despicably. “
In other words, a “bi*ch“! Now listen to CNBC’s Seema Modi (the network’s sole Indian-American on-air talent) refer to Coldwell Realty CEO Lane first as “Kamini” in introducing Ms. Lane to CNBC’s audience and beginning her first comment to Ms. Lane as “Kamini, thanks for joining us”. Heck, watch & listen to the first two lines yourselves:
What’s going on, you ask? What is going on is a display of utter ignorance on the part of CNBC’s Seema Modi & her utterly unfazed sang-froid at heaving this appalling insult on TV to another Indian-American woman guest of CNBC & that too a fellow Indian-American CEO of a national American company.
Could you imagine any loving parent naming his or her own daughter “kamini” or “bi*ch”? We cannot. So what is the correct pronunciation of the name given to their daughter by Mr. & Mrs. Rangappan, a South-Indian (presumably Tamil) Hindu-Braahman family?
The correct pronunciation of that loving name, a most traditional Sanskrut name, given by educated Indians to their lovely & charming daughters is pronounced as “Kaamini“- meaning a “loving, desirable, or beautiful woman“.
There is another huge gulf between the two names Kamini & Kaamini.
- The adjective “Kamini” as used by CNBC’s Seema Modi is of Urdu-Hindi descent, Urdu being a predominantly North-Indian Muslim name & the official language of na-Pakistan. The adjective “Kamini” has been used in numerous Bollywood films to put down a woman as a “bi*ch”.
- In utter contrast, the adjective “Kaamini” comes from Sanskrut, the fountainhead of Indian Civilization and a predominantly pious loving Hindu name.
Now understand that Seema Modi is an American-born woman of non-South-Indian Parents and, to the best of our understanding, knows hardly any Sanskrut. So we understand her being ignorant but not at all of being so appallingly ignorant & racist as she exhibited herself to be. And, based on her published profile, she worked initially at CNBC-TV 18 in India. That work in itself should have sensitized her to the raw, put-down meaning of Urdu-Hindi term “Kamini”.
Frankly, the insult used by CNBC’s Seema Modi for CEO Lane is the absolute worst defamatory insult we have heard on CNBC. Shame on Seema Mody for her intensely racist ignorance & her lack of due diligence in checking the real pronunciation as “Kaamini” of CEO Lane’s name.
For the sake of completeness, allow us to repeat the advice we had given to CNBC a few years ago when Seema Modi used to cover India as her main job. We felt her ignorance, her obvious inner racism as we sensed it, made her highly, highly unsuitable for covering India. Despite all her mistakes then, Seema Mody had NEVER before, at least to our knowledge, made a horrible racist (north vs. south) blunder as she committed this week in calling Ms. Lane as “kamini”.
We had also written that using Seema Mody to cover India simply because she is of Indian-origin is a racist act on the part of CNBC. In this case, had the same “kamini” insult been used by an CNBC host of a non-Indian heritage, the impact of the mistake would have been far less horrible.
On the other hand, we feel Seema Mody has done a good job in covering Technology & Semiconductors. She clearly likes the subject & it comes across. So we would urge CNBC to let Seema Mody focus on technology & prevent the screwups as above. Being born & educated in America, she is really out of her depth & interest in deep issues like meaning of Urdu-Muslim names vs. Sanskrut-Tamil-Hindu names.
Finally, we admit we find this episode as mainly humorous. In some circles, the sight & sound of one woman calling out another woman as “kamini” or “bi*ch” is deemed as fun, especially in lower quality Bollywood films.
And this mess has ZERO religious or historical significance. So most people can laugh at it & jeer CNBC. But, presumably, the Versant management team may not use it as comedy. So for them, we have a couple of suggestions:
- One of the worst linguistic mistake in pronouncing Indian names is to mix up names with “a” at the beginning with names with “aa” at the beginning.
- Do not necessarily go looking for an Indian-American origin people to host Indian or Indian-American guests. That is more likely to backfire in a bad way.
- Finally, instruct CNBC hosts to ask Indian-origin guests ON AIR how they would prefer to have their names pronounced. Just think, had Seema Mody simply asked Ms. Lane how she would prefer to be addressed, the above disastrously shameful mess would have been avoided.
We have not been able to find YouTube clips where the kamini insult is used to address a woman. But there is no shortage of songs in praise of a woman’s beauty. Below we present a famous semi-classical song in praise of a beautiful, accomplished woman. Listen from 00:44 seconds for about 60 more seconds or so to hear the absolutely perfect pronunciation of “Kaamini”.
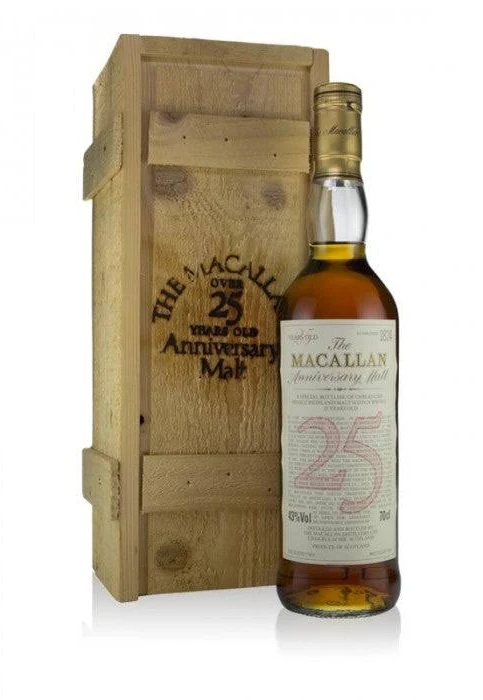
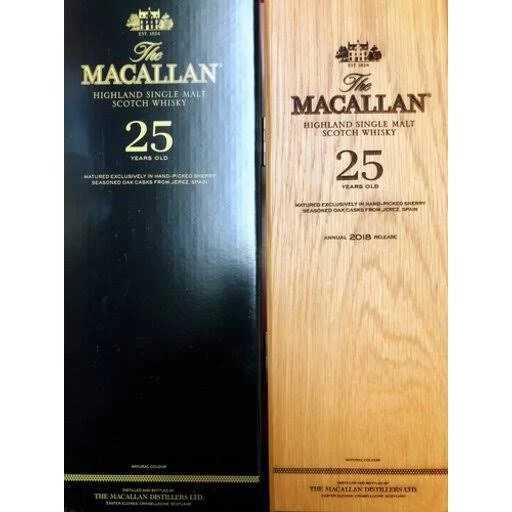
Thank you Ms. Seema Mody for making it fun & adventurous to watch CNBC! For that it would be a pleasure to buy you a drink, but only a drink we can afford, starkly unlike the mucho elite single Malts that Melissa Lee insists on, as she said once on CNBC. If we recall correctly, that was one of the two below:
Send your feedback to editor.macroviewpoints@gmail.com Or @MacroViewpoints on X.
